
Cash Buyer, Mortgage Buyer, Homeowner, or Builder: Where Do You Fit?
Today’s housing market looks different depending on where you stand. Cash buyers, buyers using a mortgage, homeowners holding onto a low rate, and builders with homes to sell each face a different set of choices. Knowing where you fit can shape your buying or selling strategy. Ryan Serhant, CEO of SERHANT, agrees:
“Today’s housing market isn’t one shared experience. It’s four very different realities.”
Here’s how each one works and why it matters to your next move.
Cash Buyers: About 1 in 4 Purchases Are All Cash
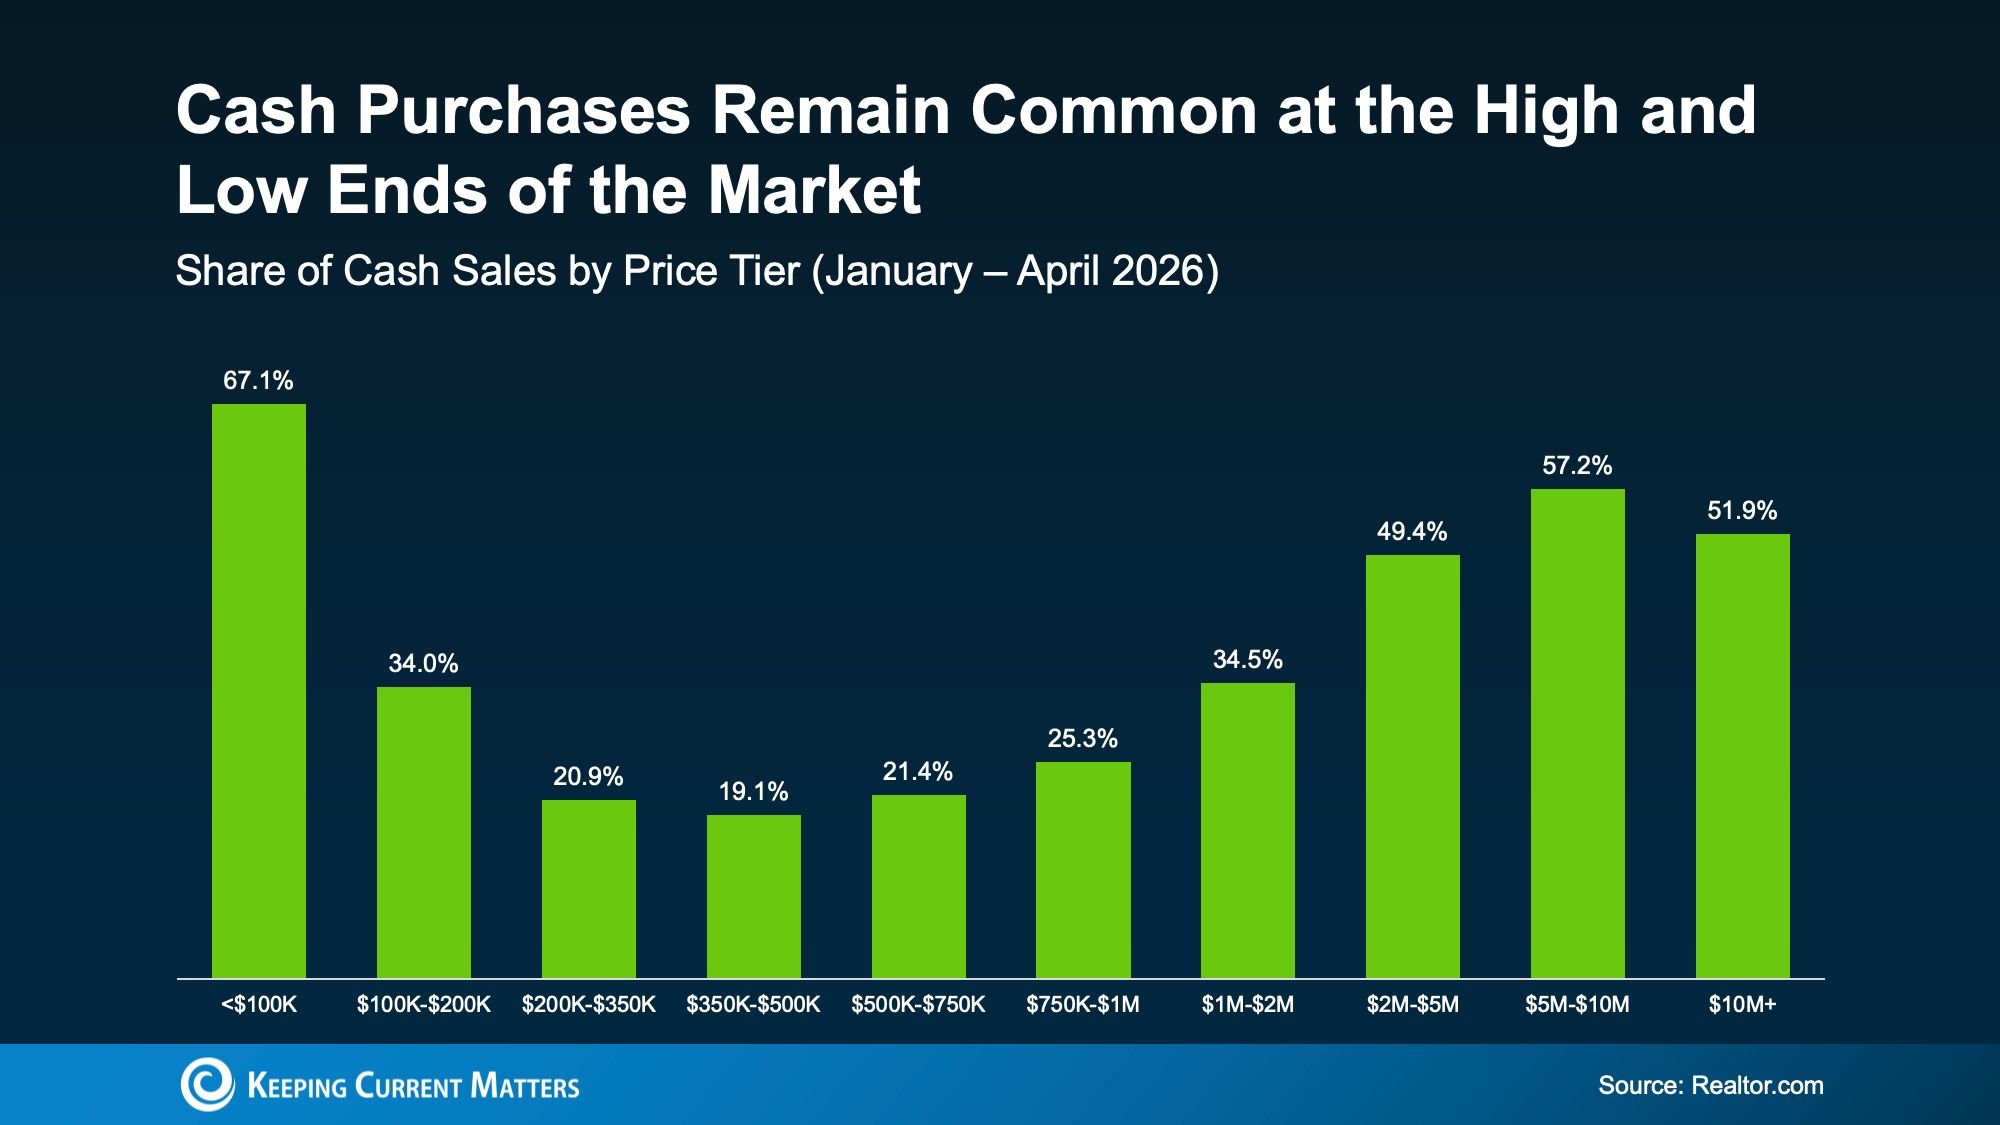
If you own a home, the equity you’ve built could help you pay cash for your next one. According to the National Association of Realtors (NAR), 26% of existing home sales this summer were all cash. That’s about 1 in 4 buyers purchasing without a mortgage.
Realtor.com data shows cash purchases are most common at both ends of the price range—the lowest and highest priced homes (see graph below):
For Buyers: If you can pay cash, an offer without a financing contingency may stand out to sellers. It could also help you close sooner and give you more room to negotiate.
For Sellers: A cash offer can reduce the risk of financing delays or a failed loan, but it may come in below other offers. Compare the price, terms, and likelihood of closing before you decide.
Buyers Using Financing: Rates Remain a Challenge, but Sellers May Offer Relief
If you’re planning to use a mortgage, don’t count on rates dropping soon. According to Fannie Mae, nearly half of the experts it surveyed raised their longer term rate forecasts this year (see graphs below):
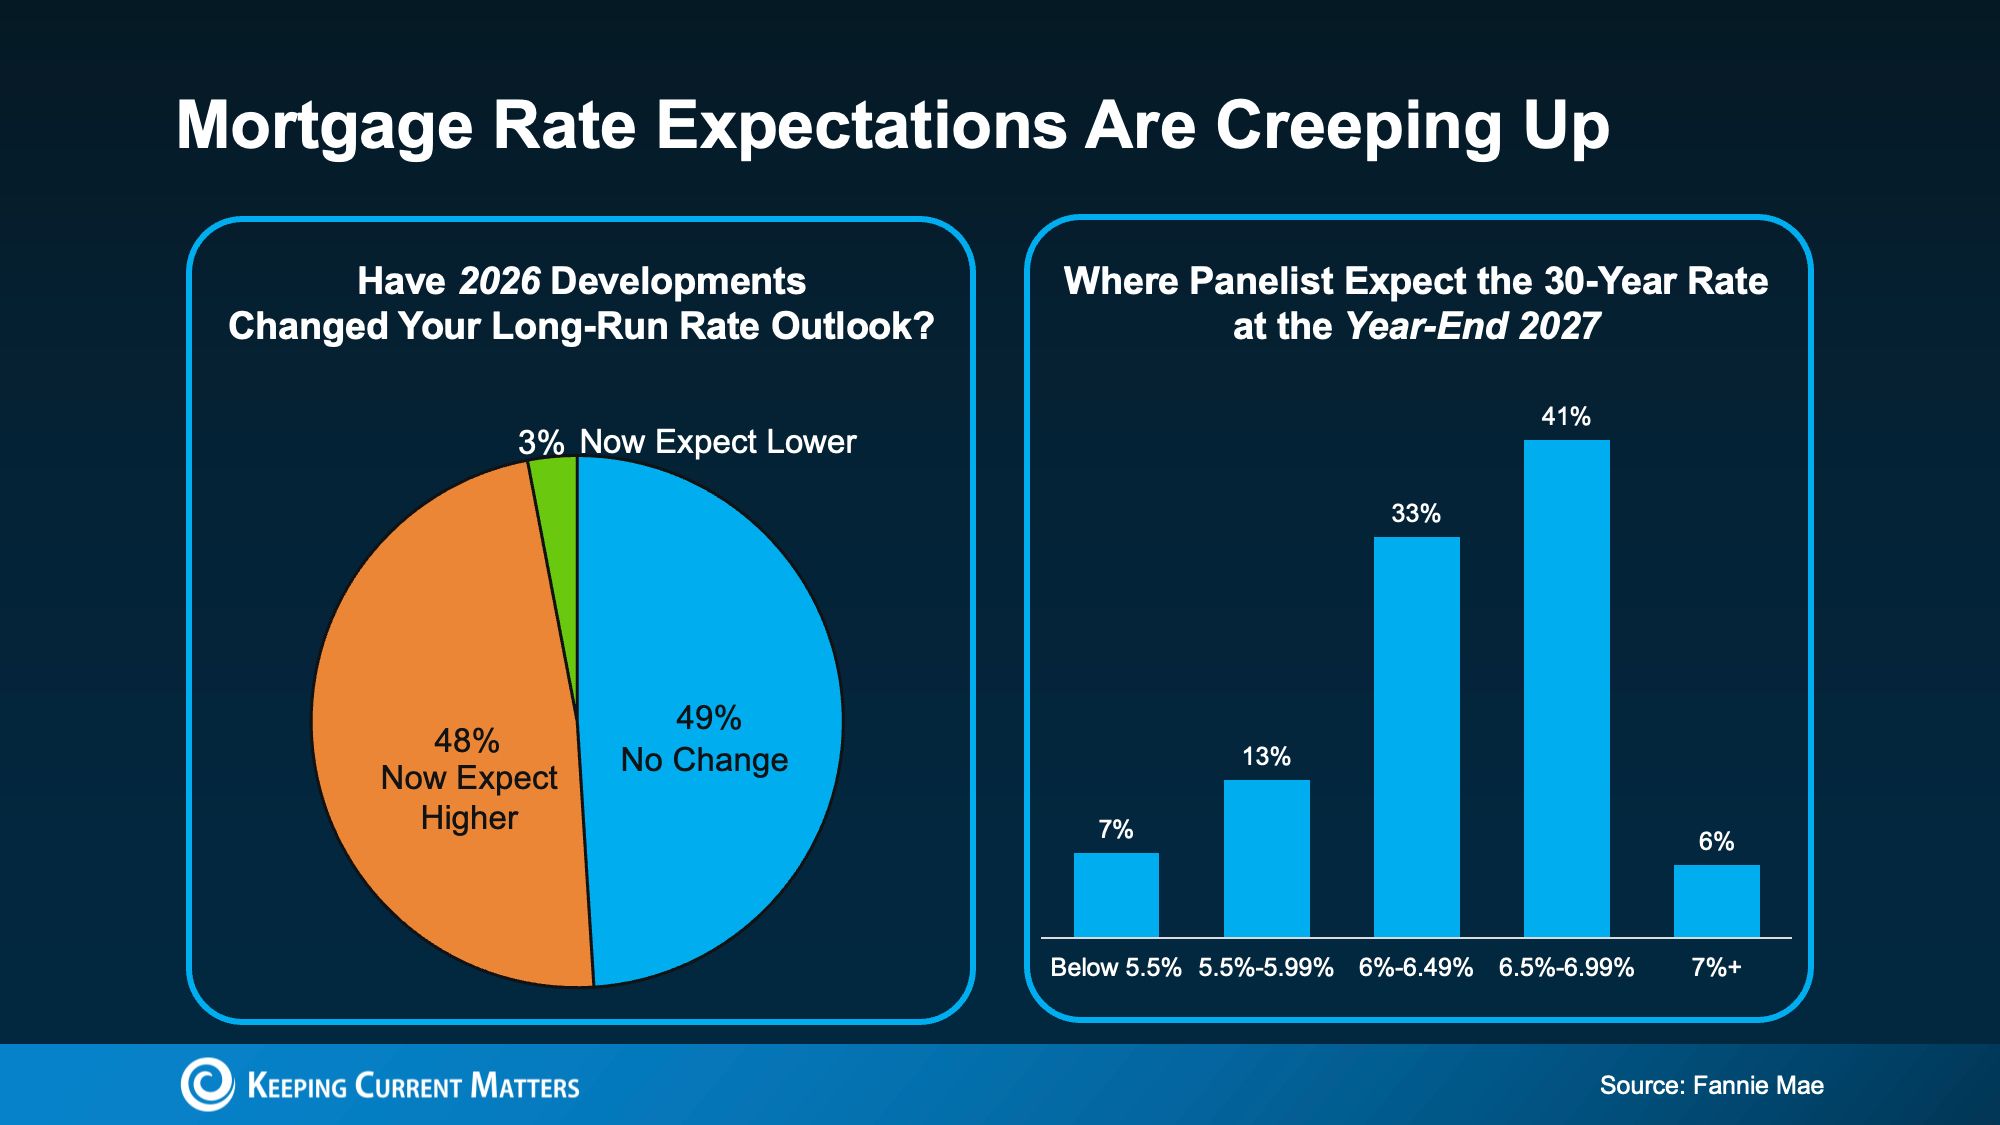
Higher rates are especially challenging for buyers who need a mortgage, including many first-time buyers. But you may have more room to negotiate with sellers.
According to Redfin, nearly half of May home sales included a seller concession, such as a credit toward closing costs or a mortgage rate buydown. Those terms could help make a purchase more affordable.
For Buyers: If the monthly payment fits your budget, consider asking for a seller concession that helps with closing costs or buys down your rate. You can evaluate the deal based on today’s numbers rather than a hoped-for rate drop.
For Sellers: Be prepared for buyers to request concessions. Factoring that possibility into your pricing strategy from the start may help you reach a deal.
Homeowners with Low Rates: Most Have a Mortgage Below 5%
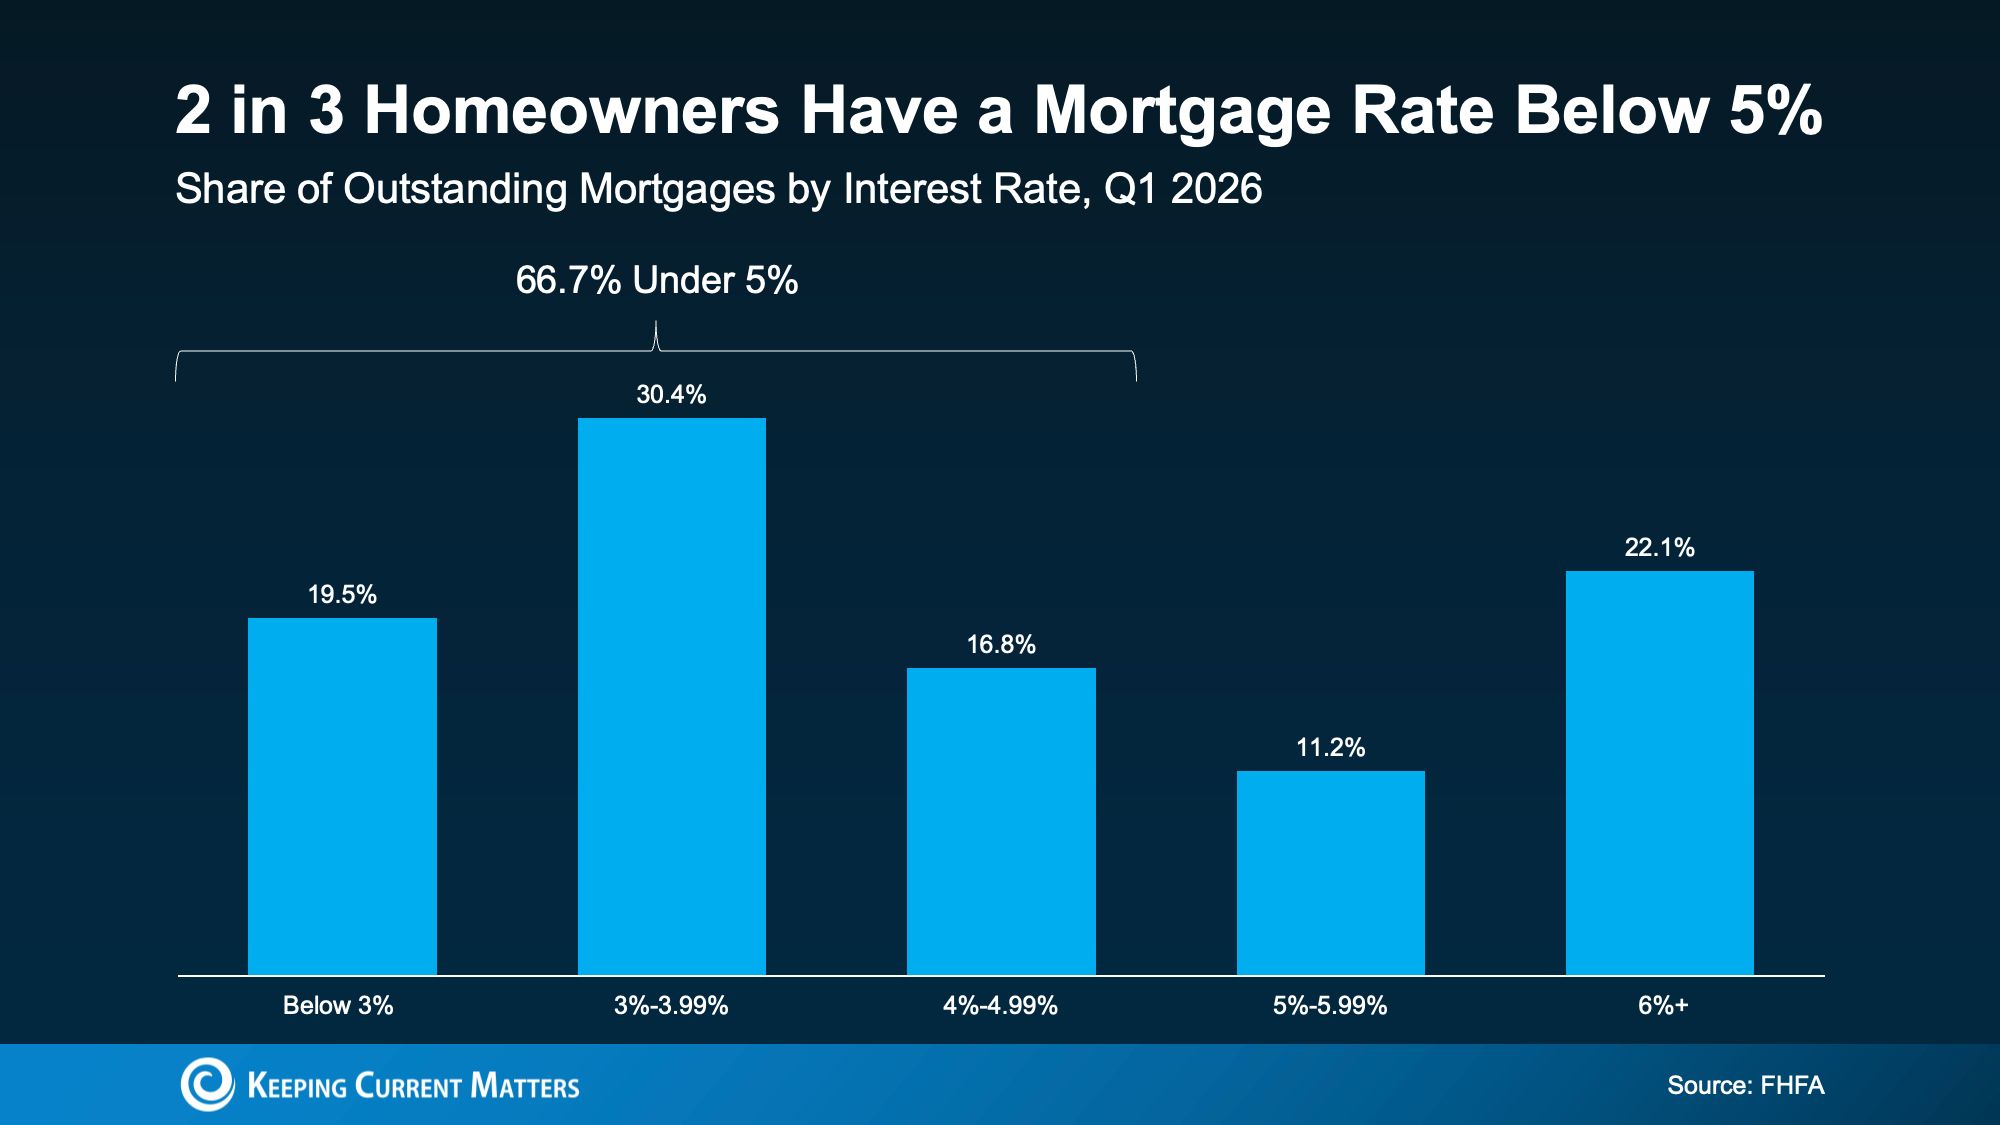
If you already own a home, giving up your current mortgage rate may make moving a harder decision. You’re in good company: roughly 2 in 3 homeowners have a rate below 5%, according to Federal Housing Finance Agency data (see graph below).
Selling would mean leaving that rate behind and, for many owners, taking on a higher one with their next mortgage. That’s why they’re described as “rate locked.”
And according to Fannie Mae, most experts expect the mortgage rate lock-in effect to last another three to five years. That could continue to limit the number of homes listed for sale.
For Buyers: Homeowners who list despite a low mortgage rate often have a specific reason to move. Learn what matters to the seller; it may reveal room to negotiate on timing or terms.
For Sellers: Before ruling out a move, calculate what your equity could put toward your next home. If you have an FHA or VA loan, ask your lender whether an eligible buyer could assume it, subject to approval.
Homebuilders: There May Be More Room to Negotiate Than You Expect
If you’re considering new construction, you may have room to negotiate. The latest U.S. Census data shows nearly 10 months of new-home supply at the current sales pace, above the typical four to six months. With more unsold homes available, some builders are offering price reductions and mortgage rate buydowns to attract buyers.
For Buyers: New construction may offer opportunities to negotiate. Work with your own agent and compare the full package, including price, rate buydowns, closing-cost credits, and any conditions attached to the incentives.
For Sellers: Highlight the advantages your home offers, such as mature landscaping, an established neighborhood, and a move-in date that doesn’t depend on construction. Those details can help buyers see its value alongside a new build.
Bottom Line
Cash buyers, buyers using financing, homeowners with low mortgage rates, and builders each face different opportunities and tradeoffs. Your best strategy depends on where you fit and what’s happening in your local market.
Let’s talk through your options and build a plan around your goals.
Categories
Recent Posts

GET MORE INFORMATION
