
3 Credit Score Changes That Could Affect Your Mortgage
What credit score do you really need to buy a home? If you have a specific number in mind, you might be surprised to learn it’s not necessarily accurate. And with changes underway in how credit scores are calculated and evaluated, the answer is becoming less straightforward—but potentially more favorable for homebuyers.
Here’s what you should understand about these changes and how they could impact your path to homeownership.
#1 Most People Are Just Guessing
Since 2015, Fannie Mae has been studying what consumers believe is required to qualify for a mortgage. Their research consistently shows that many potential homebuyers think they need a higher credit score than lenders actually require. In 2023, the average estimated minimum score was 652.
However, the traditional minimum credit score for many loans backed by Fannie Mae and Freddie Mac has been 620. And with recent changes to mortgage lending guidelines, even that number isn't necessarily a strict requirement for every loan they back.
A more recent survey by Veterans United reinforces this misconception, revealing that many consumers still believe qualifying for a mortgage requires a higher credit score than it actually does: See another version
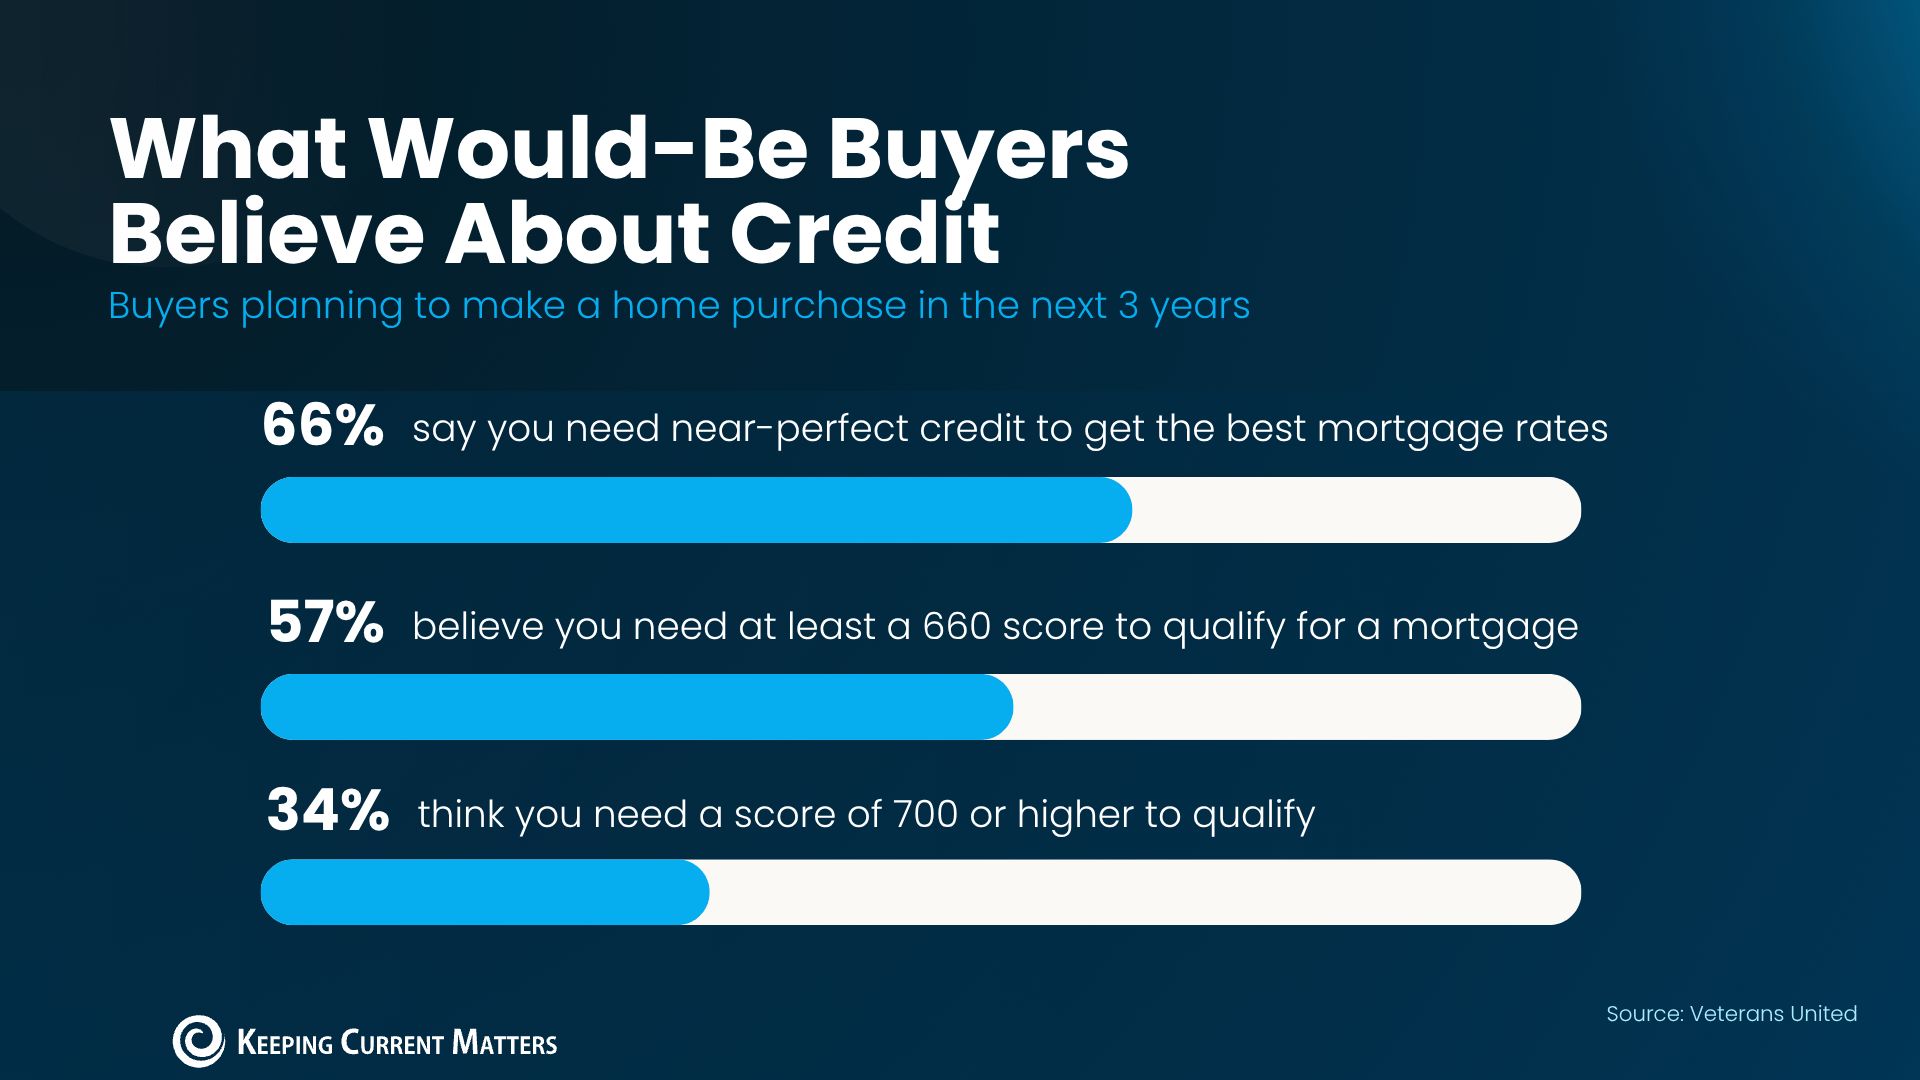
The key takeaway? Assuming you won’t qualify could cost you an opportunity.
Renters who believe their credit score is too low to qualify for a mortgage may never explore their financing options or discover that homeownership could be closer than they think. Is this conversation helpful so far?
#2 Credit Score Requirements Are Evolving
For years, mortgage lenders have primarily relied on Classic FICO scores to evaluate borrowers. But efforts to increase competition, expand access to credit, and create more opportunities for homeownership are reshaping the industry. The Federal Housing Finance Agency (FHFA) has approved newer credit scoring models, including FICO 10T and VantageScore 4.0.
These updated models can produce different credit scores for the same borrower. According to VantageScore, its model can evaluate approximately 33 million adults who couldn't be scored using Classic FICO. That means the credit score you check through an app may not match the one your mortgage lender uses.
What's important to understand? While credit scoring models are evolving, the fundamentals of maintaining good credit remain the same.
#3 Strengthen Your Credit and Work With an Expert
Your credit score remains an important factor in qualifying for a mortgage, regardless of which scoring model is used. The good news is that the same smart financial habits can help strengthen your credit profile under both traditional and newer scoring systems:
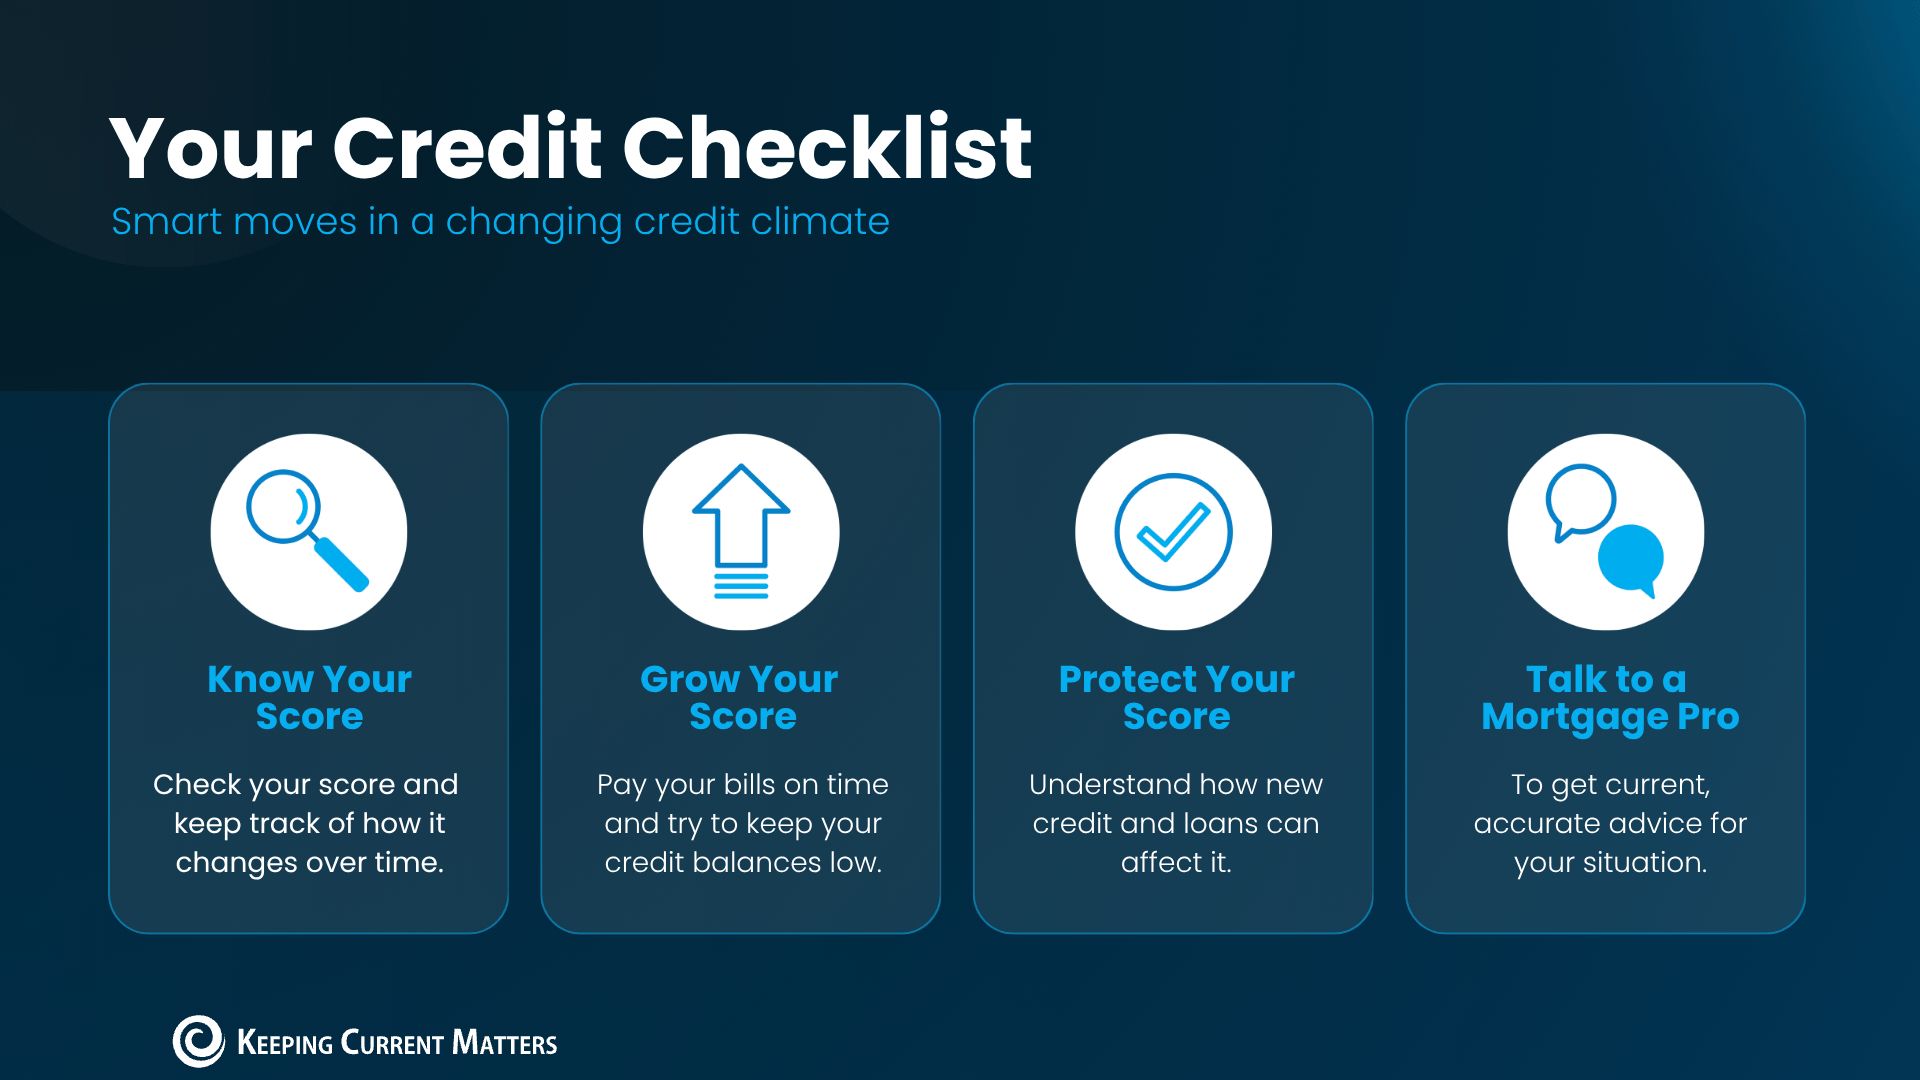
While credit scoring models continue to evolve, the steps you can take to improve your credit remain largely the same. Staying financially informed, practicing consistent habits, and maintaining a little discipline can make a meaningful difference over time.
What This Means for Homebuyers
When it comes to your credit and buying a home, don't rely solely on online calculators, credit monitoring apps, or advice from friends. With lending guidelines evolving and common misconceptions still circulating, speaking with a knowledgeable mortgage professional can help you better understand your credit, explore financing options, and determine what it takes to qualify.
Homeownership may be more attainable than you realize.
Categories
Recent Posts
GET MORE INFORMATION
